
Global e-commerce heads from $6.88T to $7.38T in 2027, digital wallets have already passed cards, and the growth is in fragmented rails — LATAM’s Pix, India’s UPI, ASEAN’s QRIS — that no single card integration can serve.
The default way the world pays online is no longer a card — and any business still building for one is building for the past.
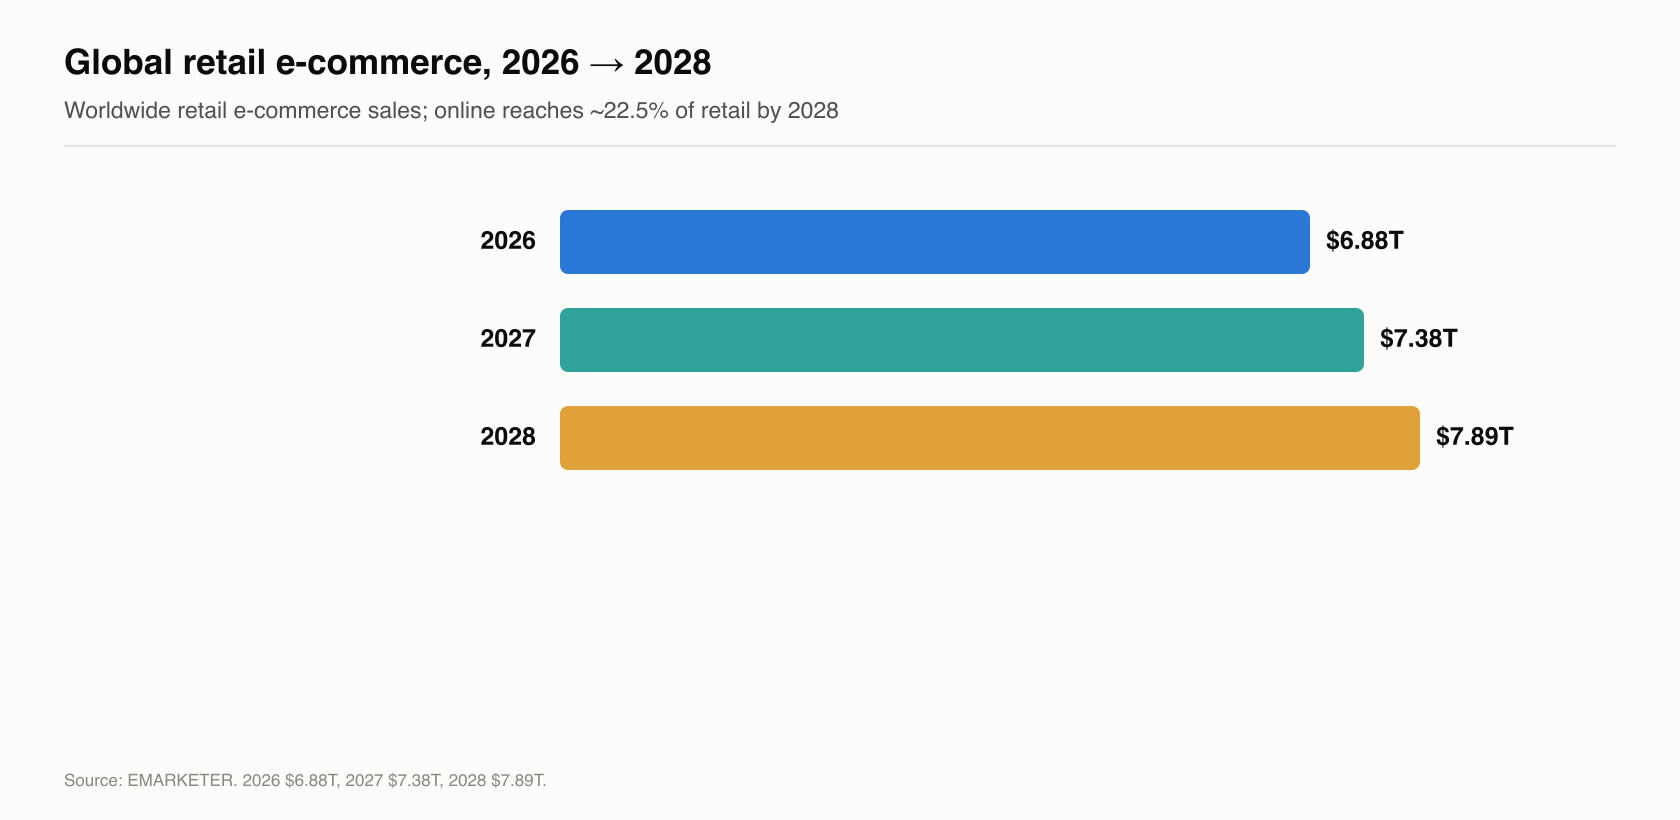
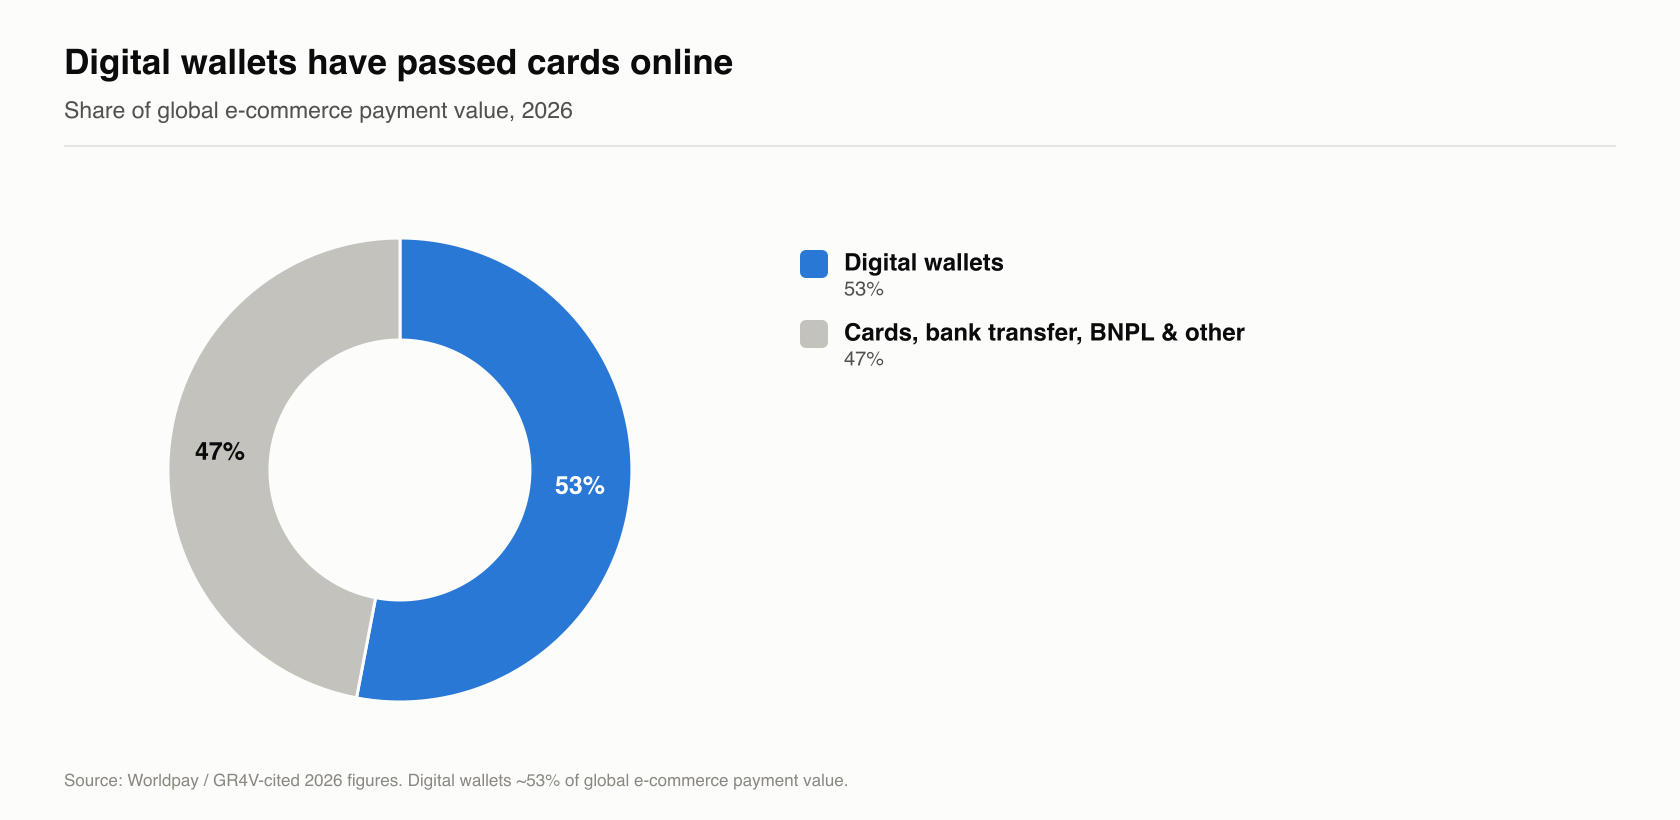
“Everyone pays with a card.” That assumption is now wrong in most of the world’s fastest-growing markets — and by 2027 it will be wrong globally. EMARKETER puts global retail e-commerce at $6.88T in 2026, rising to $7.38T in 2027 and $7.89T in 2028, with online reaching about 22.5% of all retail by 2028. But the more disruptive number sits underneath the total: digital wallets now account for roughly 53% of global e-commerce payment value — past cards. The card-default era is ending, and it is ending fastest exactly where the growth is.
The size of the prize
The top line is straightforward and large. E-commerce payment transaction value runs to about $8.1T in 2026, and the retail e-commerce base keeps compounding through 2028. What changes the operating problem for any business selling across borders is not the size but the fragmentation of how that value moves. A single global total masks a dozen dominant local rails, each with its own settlement behaviour.
Wallets past cards — and real-time rails accelerating
The headline shift is that digital wallets have overtaken cards, at roughly 53% of global e-commerce payment value. But “wallet” means different infrastructure in different places, and the real-time account-to-account systems underneath are growing faster than anything cards ever did. Per the figures tracked here, Pix, UPI and mobile money are projected to grow at about 35%, 18% and 16% a year respectively through 2027.
The regional data makes the scale concrete. In Brazil, EBANX reports Pix values grew 34% to $6.3T in 2025 across 79.7B transactions (up 26%), and Pix Automático could add $30B+ in recurring online payments within two years — a direct opening for subscription commerce on a rail that isn’t a card. In India, UPI cleared 228.3B transactions in 2025, up 33% year-on-year, worth $3.4T (up 21%). Indonesia’s QRIS handled 18.6B transactions in 2025, up 47%. These are not pilots; they are the default way hundreds of millions of people now pay.
Notice the growth rates against the base. Pix compounding at roughly 35% a year, UPI at about 18%, mobile money at about 16% — these are the fastest lanes in payments, and none of them is a card network. For a merchant, the strategic implication is uncomfortable: the rails growing fastest are precisely the ones a card-first checkout handles worst. Pix Automático is the clearest example. A rail that can carry recurring, subscription-style billing without a card turns the entire “card on file” model on its head in the largest economy in Latin America — and it arrives within a two-year window, not a distant forecast horizon.
Where the growth actually is
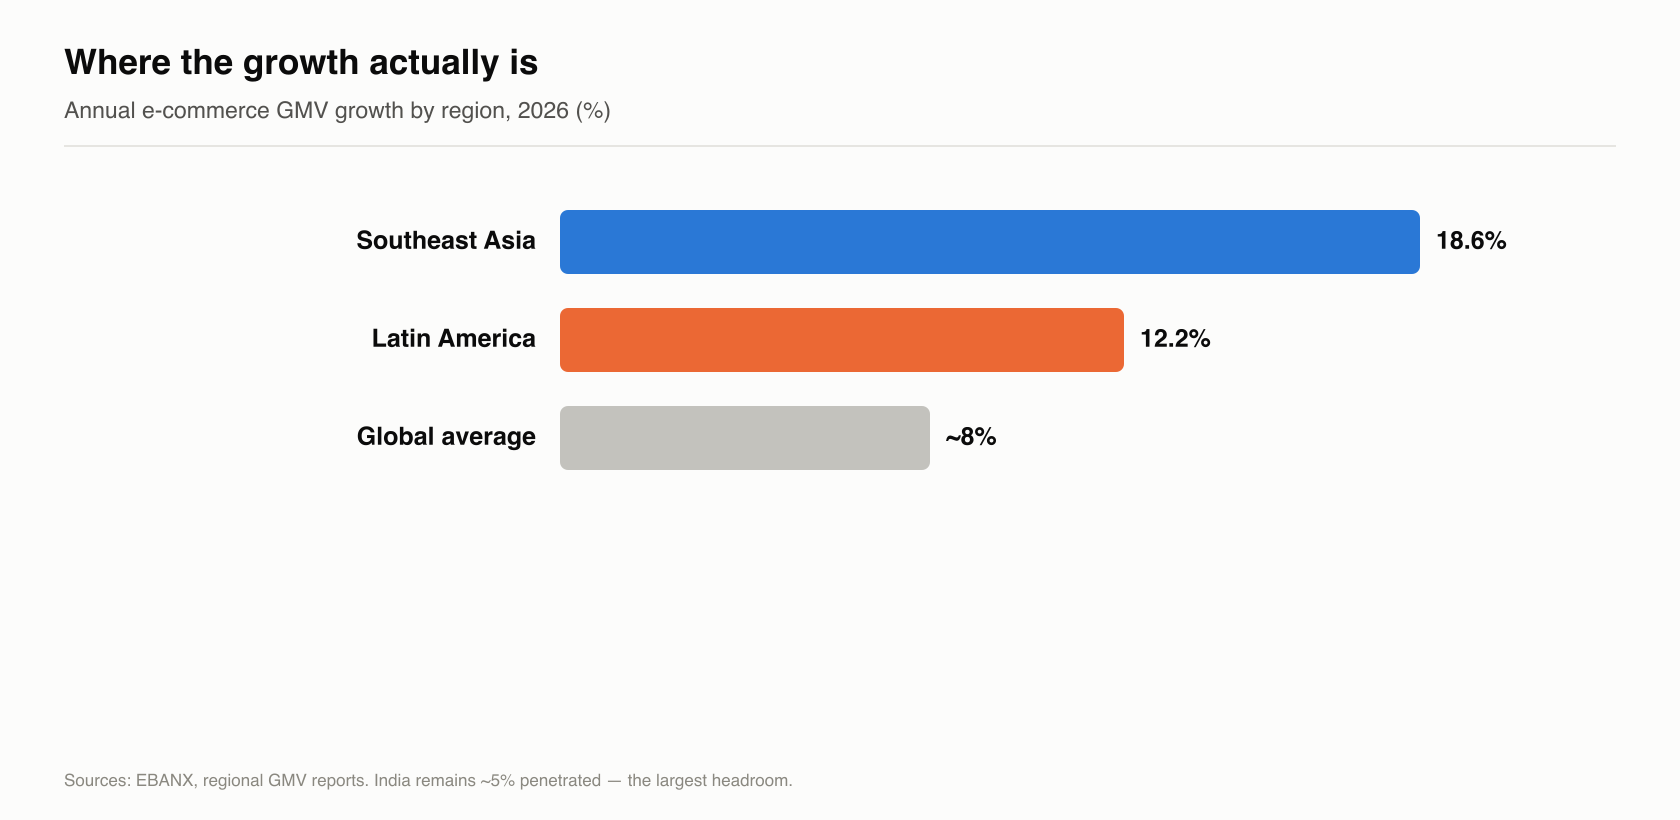
The mature card markets still matter, but the momentum is elsewhere. Latin America is the fastest-growing regional market at 12.2% (2025), with e-commerce transaction volume on track past $760B, up 12%. Southeast Asia is the fastest-growing e-commerce region outright — roughly 18.6% GMV growth toward about $230B GMV by 2026, and by 2027 an estimated 402M online shoppers, close to 88% of the population. India offers the starkest headroom: e-commerce is only about 5% penetrated in a 1.4B-person market. The Gulf leans on wallets; the US, UK and Canada remain card-and-wallet markets but are no longer where the curve bends.
The regional payments map
Put the growth rates next to the dominant rails and the operating challenge is obvious: there is no single “checkout” that serves this market. Each region settles differently.
| Region | Growth + dominant rail (2026–2027) |
|---|---|
| United States | Largest, mature market; cards and wallets dominant; steady rather than fast growth. |
| Latin America | Fastest-growing region at 12.2% (2025); Pix leads — $6.3T in value, 79.7B transactions; Pix Automático opening recurring payments. |
| South Asia / India | ~5% e-commerce penetration in a 1.4B market; UPI dominant — 228.3B transactions, $3.4T value in 2025. |
| ASEAN / Southeast Asia | Fastest-growing e-commerce region, ~18.6% GMV growth to ~$230B by 2026; QRIS and wallets lead (Indonesia QRIS 18.6B txns, +47%). |
| Middle East / Gulf | Wallet-led digital commerce; strong sovereign-backed digital investment. |
| United Kingdom | Mature market; cards plus wallets; strong fintech and retail-media ecosystem. |
| Canada | Mature North-American market; cards plus wallets; aligns with US trends. |
| China | Wallet-native at scale; account-to-account and QR the default. |
| EU | Mixed cards and wallets; real-time and account-to-account rails rising under regulatory push. |
Nine regions, and no two settle the same way. Pix in Brazil, UPI in India, QRIS in Indonesia, wallets in the Gulf, cards-plus-wallets across the mature West. Selling globally in 2027 means clearing on all of them.
The temptation is to chase only the mature markets and let the local rails wait. The penetration figures argue against it. India at roughly 5% e-commerce penetration in a 1.4B-person market, and Southeast Asia heading toward 402M online shoppers — close to 88% of its population — by 2027, are not edge cases to bolt on later. They are where the next decade of net-new commerce is created, and they are wallet- and account-to-account-native from the first transaction. A business that treats them as an afterthought is treating the growth itself as an afterthought.
Why this is an architecture problem, not an integrations problem
Here is the trap most commerce stacks fall into: they treat each rail as a bespoke integration. Add Pix, add UPI, add QRIS, add three wallet providers, add cards — and you accumulate twenty brittle integrations, each with its own settlement quirks, each a separate reconciliation headache. The fragmentation that is a market opportunity becomes an engineering liability.
The structural fix is a payment core — a provider-agnostic layer where a new rail is a configuration, not a rewrite — sitting under invoice-centric commerce so that however a customer pays, the same line item settles the same way. Pix, a card, a wallet, or non-custodial crypto all resolve against one invoice, one reconciliation model. That is the difference between adding a market in an afternoon and adding it in a quarter.
This is where a proportionate, honest recommendation is warranted. VBWD is built on exactly that principle: a self-hosted, source-available full-stack SaaS SDK with a provider-agnostic payment core and non-custodial settlement, where adding a new gateway takes roughly 100× less code than a bespoke integration. It is invoice-centric, so every rail settles the same line item; MCP-native, GDPR-first, and multi-tenant, with an agnostic core and toggleable plugins so you enable a market without re-architecting. For a business planning to sell across Pix, UPI, QRIS and wallets at once, the payment core is the point — not another integration backlog. The design is documented at vbwd.cc/docs, the project at vbwd.cc, and the source at github.com/VBWD-platform/vbwd-sdk-public.
The 2027 payments map is not one market getting bigger; it is many rails growing at once, with wallets and real-time systems displacing the card default region by region. The businesses that capture the $7T-plus opportunity will be the ones that stopped building checkouts and started building a payment core.
Written for Red Robot with AI assistance and human editing. Figures from the firms cited; forecasts are estimates, not guarantees.


