
Global AI spend is enormous but the estimates diverge wildly; the real story of 2026–2027 is concentration (US 38%, China 26%) and the rise of sovereign AI across the Gulf, ASEAN and India.
The global AI market is either a $540 billion business or a $620 billion one, depending on who you ask — and that gap is the first thing to understand about 2027.
“Follow the money” is the only honest way to read the 2027 AI market — because almost nothing else about it is agreed on. Ask three research firms how big artificial intelligence already is and you get three different countries’ worth of GDP: Grand View pegs 2026 at $539.5B, MarketsandMarkets at $602B, and Statista at $617.6B. The headline forecasts diverge wildly, but the capital flows do not. Follow those, and the 2027 map draws itself — a market compounding at roughly 30–36% a year, concentrated in a handful of geographies, and increasingly defined by who controls their own AI and data path rather than who rents it.
One market, three price tags
Start with the caveat, because it is the story. Estimates for the 2026 AI market run from about $540B to $620B depending on how each firm draws the boundary around “AI” — models, infrastructure, applications, services, or some blend. That is a spread of nearly $80B on a single year, and it should make anyone quoting a precise 2030 number suspicious. What the firms broadly agree on is the slope: a consensus compound annual growth rate in the low-to-mid 30s percent into the late 2020s. When the levels disagree but the growth rate holds, the sensible read is directional — the market roughly doubles on a two-to-three-year horizon — not a bet on any single vendor’s decimal point.
So the useful question is not “how big” but “whose.” And on that, the data is far less ambiguous.
The US–China split, and everyone else
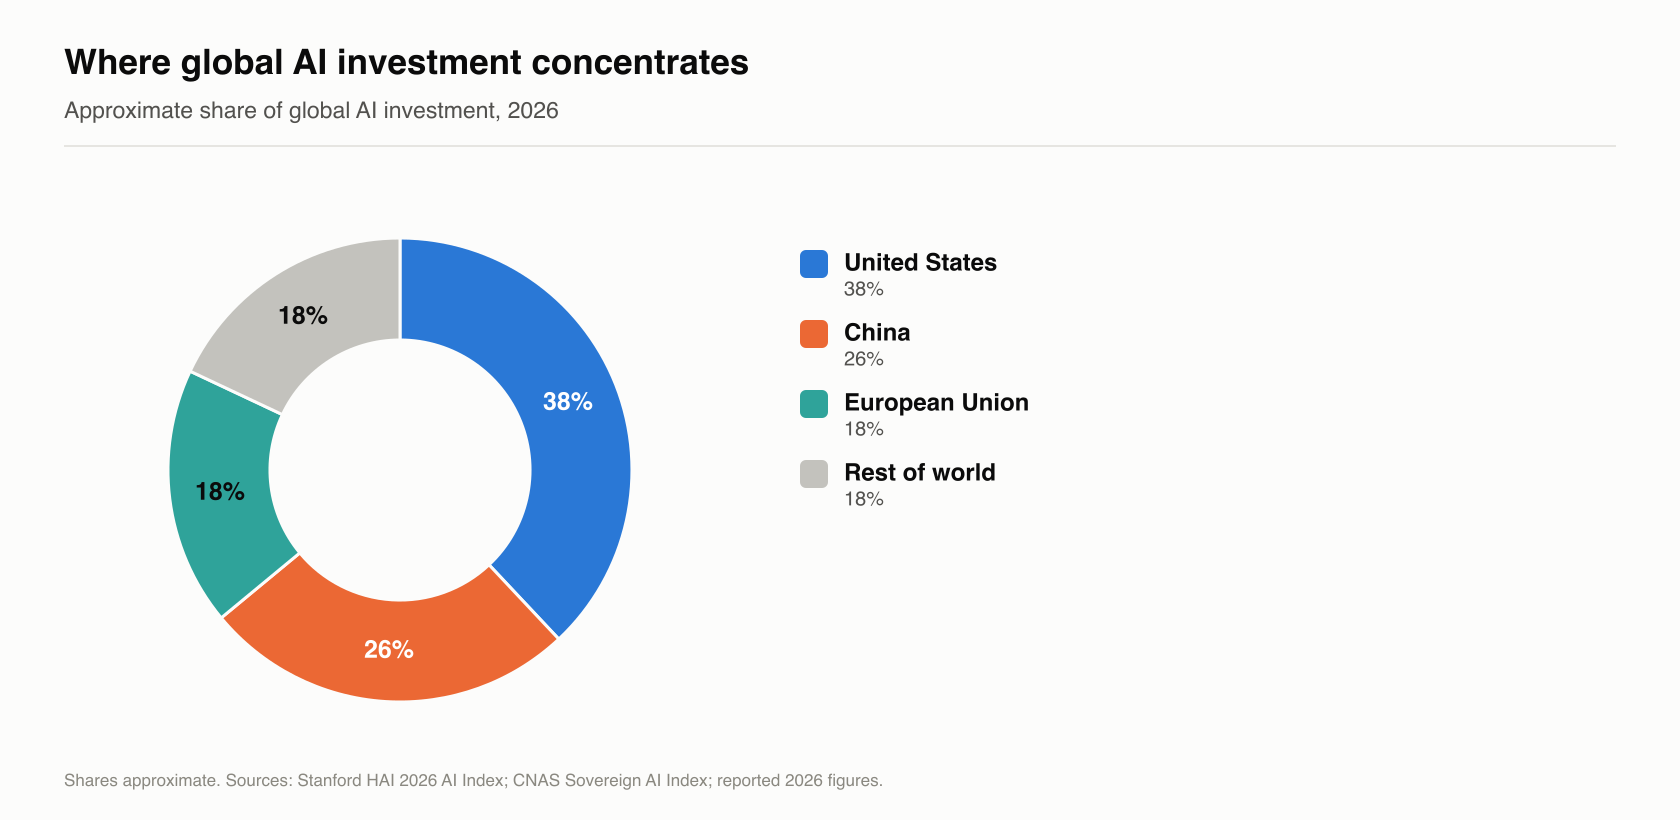
By investment share, global AI is a two-power system with a long tail. The United States accounts for roughly 38% of global AI investment, China 26%, the EU 18%, and the rest of the world the remaining 18%. That split understates how lopsided the private-capital picture is. According to the Stanford HAI 2026 AI Index, US private AI investment reached $285.9B in 2025 — about 23 times China’s $12.4B. The US is not merely first; on private money it is in a category of one.
China’s strength shows up on different axes. It leads on AI patents, has committed a $47.5B semiconductor fund to close the hardware gap, and is running autonomous-vehicle testing across 16 cities — a state-directed build-out that private-investment tallies miss. Europe, at 18% of investment share, is large enough to set rules the rest of the market must follow but is not competing dollar-for-dollar on private capital. The interesting movement, then, is in the tail — the “rest of world” 18% that is no longer passive.
The sovereign-AI wave
The most consequential shift on the 2027 map is money that does not want to be a customer of the two leaders. Sovereign AI — nations and their wealth funds building domestic compute, models and data centres — is concentrating fast. The Middle East and East Asia together account for more than 80% of tracked sovereign-AI investment. Saudi Arabia’s “Project Transcendence” carries a $100B commitment, and Gulf sovereign wealth funds committed $46B to AI between January and September 2025 alone. This is capital deployed explicitly so that a country’s AI capability, and the data underneath it, stays within its borders and its control.
Southeast Asia is riding the same logic with a lighter touch, standing up local build-outs alongside its consumer-internet boom. And then there is India — the clearest headroom case on the board. Indian private AI investment was only about $1.4B in 2023, tenth globally, a rounding error next to the US figure. But it sits in a 1.4B-person market with a digital-payments backbone (UPI cleared 228.3B transactions in 2025) that most of the world would envy. Small today; structurally poised to be large.
What the regional signals actually say
Read across the regions and a pattern emerges: the leaders own the capital, the sovereign buyers own the infrastructure, and the emerging markets own the demand.
| Region | AI role / signal (2026–2027) |
|---|---|
| United States | 38% of global AI investment; $285.9B private AI in 2025 — the private-capital centre of gravity. |
| China | 26% of investment; AI-patent leader; $47.5B semiconductor fund; AV testing across 16 cities. State-directed. |
| Middle East / Gulf | Sovereign-AI hub; with East Asia, >80% of tracked sovereign-AI investment. Saudi $100B “Project Transcendence”; SWFs committed $46B (Jan–Sep 2025). |
| ASEAN / Southeast Asia | Rising sovereign-AI build-outs alongside the region’s fast-growing consumer internet. |
| South Asia / India | ~$1.4B private AI (2023, 10th globally) — small but rising fast; huge demand-side headroom. |
| EU | 18% of investment share; rule-setter more than dollar-for-dollar private-capital rival. |
| UK | Mature market; strong fintech and research; part of the EU-style data-residency conversation. |
| Canada | Deep AI-research strength; aligns with US cloud/SaaS trends; growing data-residency interest. |
| Latin America | Fastest-growing regional market at 12.2% (2025); Brazil is scrutinising minority AI stakes as competition signals. |
Two details in that table deserve underlining. First, Brazil scrutinising minority AI stakes is an early sign that regulators outside the US and EU now treat AI ownership as a competition matter — a governance story catching up to the capital story. Second, the Gulf-plus-East-Asia concentration of sovereign money means that a large slice of 2027’s new AI infrastructure will be built deliberately outside the hyperscaler default.
The through-line: own your AI path
Strip away the forecasts and the sovereign build-outs share one instinct — the businesses and states that win the next phase are the ones that own their AI and data path rather than renting it from a platform they cannot inspect. That is the same instinct, at company scale, behind self-hosting your own stack: an agent-callable, MCP-native system where the model access, the data, and the commerce logic sit on infrastructure you control.
It is worth a proportionate note here that this is buildable today. VBWD is a self-hosted, source-available full-stack SaaS SDK — an agnostic core with toggleable plugins, MCP-native so agents can call it directly, and GDPR-first — for teams that would rather own that path than rent a black box. You can read the approach at vbwd.cc or the source at github.com/VBWD-platform/vbwd-sdk-public. Not a requirement for playing in this market — just an example of the ownership posture the sovereign-AI wave is expressing at nation scale.
The 2027 AI map, then, is less a size chart than an ownership chart. The estimates will keep disagreeing on the total. The capital, the sovereign infrastructure, and the demand-side headroom all point the same direction: toward whoever controls the path, not merely whoever rents the output.
Written for Red Robot with AI assistance and human editing. Figures from the firms cited; forecasts are estimates, not guarantees.


