
Public cloud crosses $1 trillion on trend in 2027 even as a sovereignty-driven counter-move pulls workloads back home — geopatriation rising from 5% to 75% of EU and Middle-Eastern firms by 2030.
Two things are true about the cloud in 2027: it has never spent more, and it has never trusted itself less.
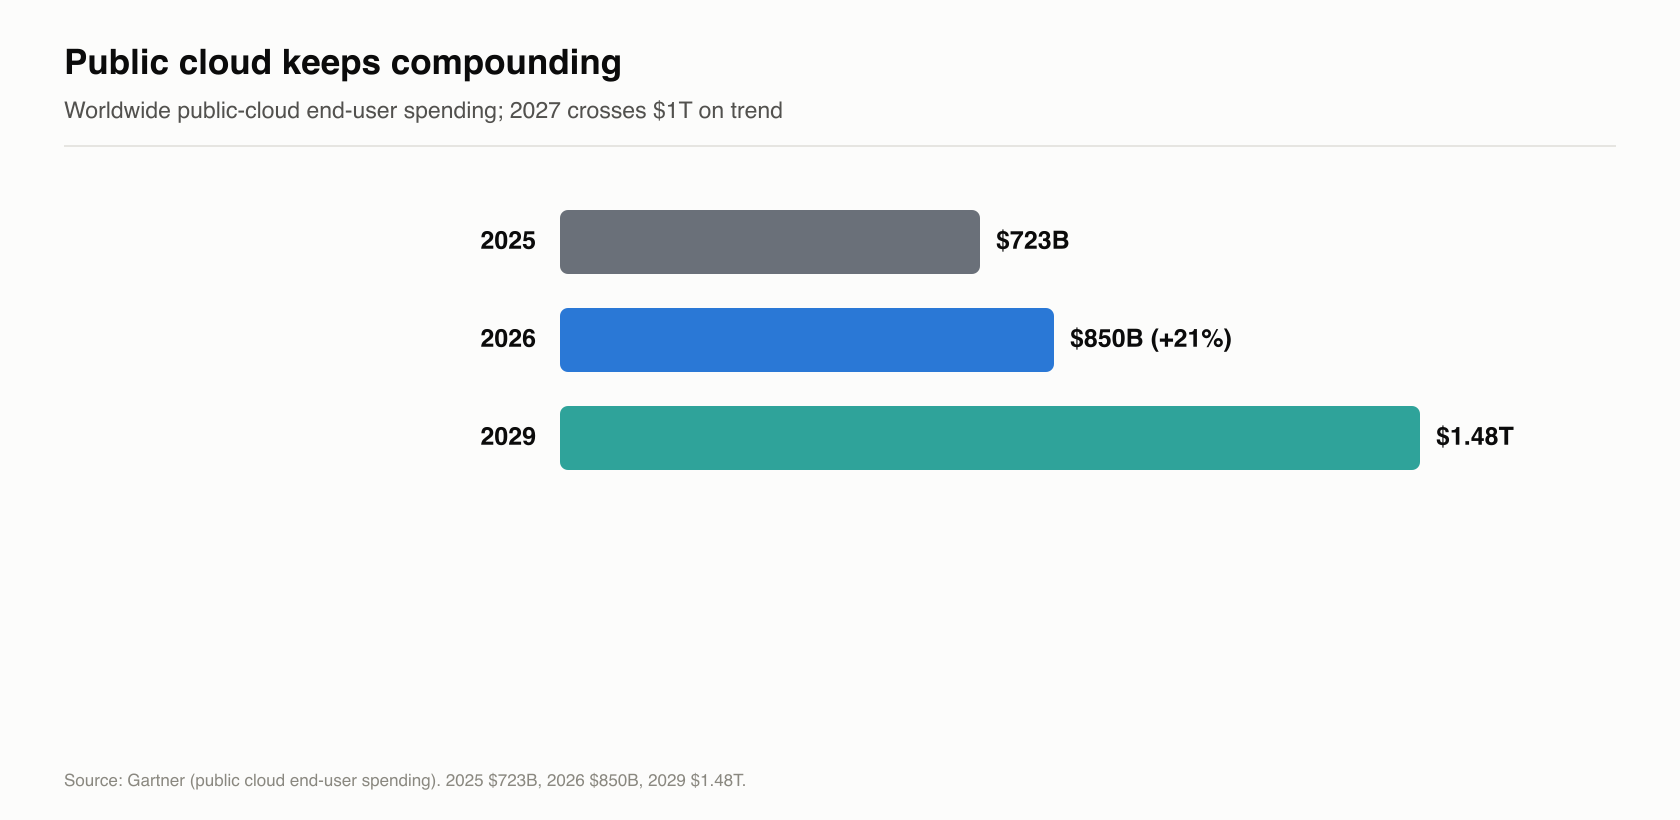
“The cloud is inevitable” — that was the line for a decade, and in 2026 the spending proves it. What the spending hides is a countertrend now moving fast enough to reshape the map. Gartner has public cloud end-user spending going from $723B in 2025 to $850B in 2026, a 21% jump, and on to $1.48T by 2029 — crossing the $1T mark on trend in 2027. The boom is real. But underneath it, a growing share of firms are quietly pulling workloads back under their own control. Both things are true at once, and 2027 belongs to the operators who understand why.
The $850B boom, in context
Cloud is no longer a line item; it is the substrate. Worldwide IT spending reaches $6.37T in 2026, up 14.2%, and public cloud is the fastest-compounding slice of it. Within that, software-as-a-service is the engine: SaaS was roughly $408B in 2025 and is set to make up about 54% of cloud revenue in 2026, on a path to cross $1T before 2035. The newest accelerant is AI itself — AI workloads account for 19% of cloud spend in 2026, up from just 8% in 2023. In three years AI has more than doubled its share of the cloud bill.
Read those numbers straight and the conclusion looks obvious: consolidate everything onto the hyperscalers and ride the curve. That was the correct answer for most of the 2010s. It is now only half the answer.
The quiet countertrend: geopatriation
The other half has a name Gartner uses: geopatriation — relocating workloads back within a jurisdiction for sovereignty reasons. And the projected slope is steep. The share of European and Middle-Eastern firms that have relocated workloads for sovereignty is forecast to rise from 5% in 2025 to 75% by 2030. That is not a rounding-error movement; it is a majority of a major market changing its posture inside five years.
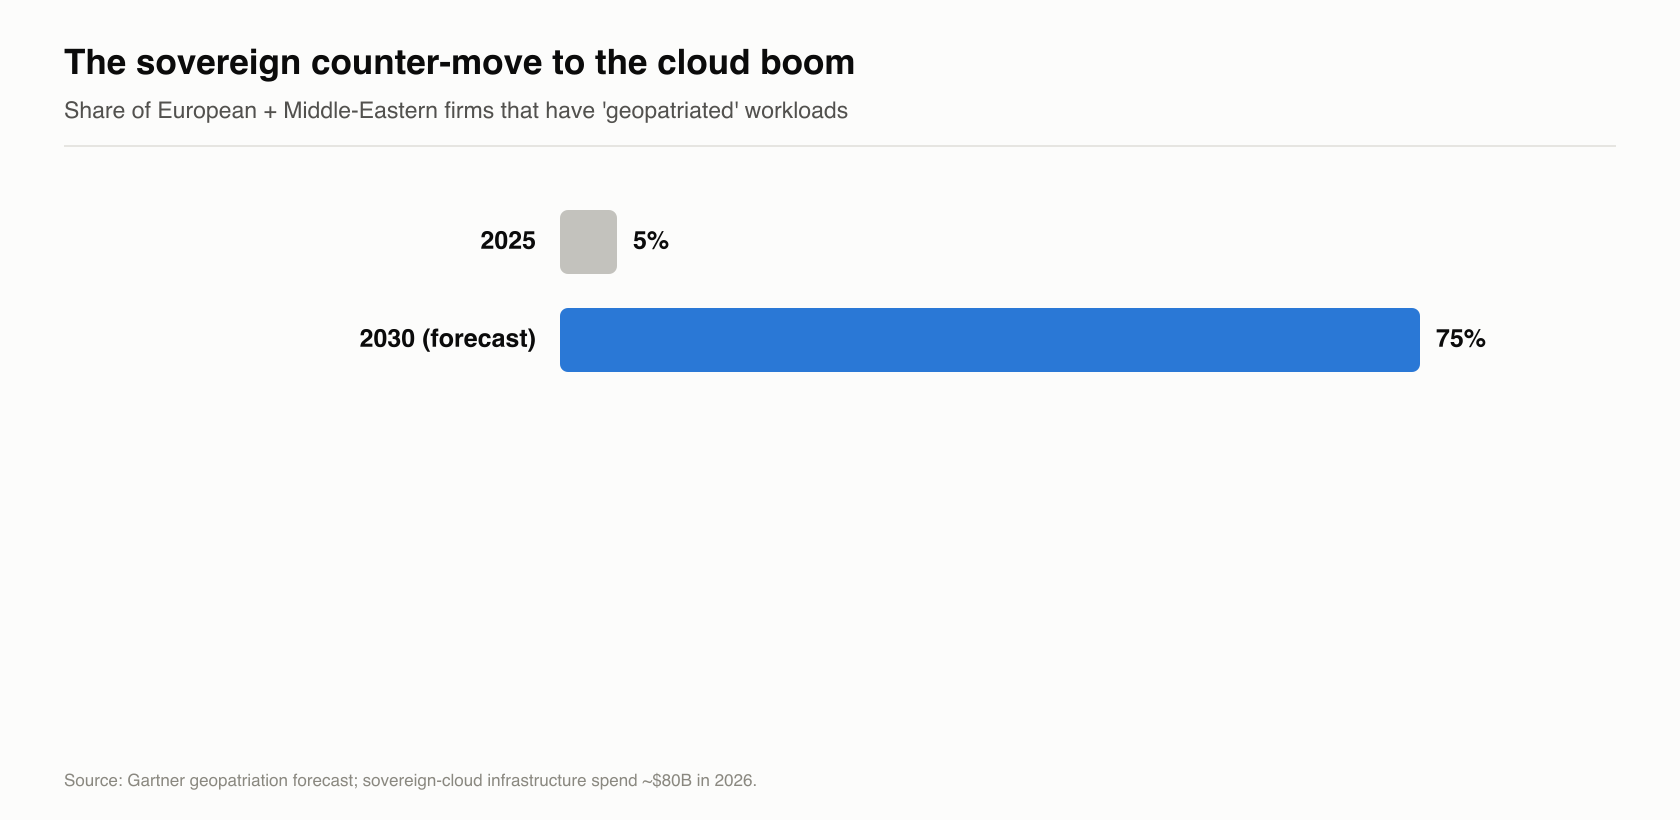
The demand is already capitalised. Sovereign cloud IaaS is projected at roughly $80B in 2026 by Gartner, and the drivers are concrete regulation rather than sentiment — the EU’s NIS2 directive and France’s “Cloud de Confiance” framework chief among them. A crop of European alternatives is positioned to absorb the shift: OVHcloud, Scaleway, Hetzner and Exoscale. The catch is cost. Sovereign deployments carry a premium of roughly 10–30% over commodity public cloud. Firms are choosing to pay it, which tells you the driver is not price optimisation — it is control.
That premium is the tell. In a decade where every other cloud decision optimised for unit cost, a majority of a major market is now willingly paying 10–30% more for jurisdictional certainty. When buyers pay up for a property that has nothing to do with performance or price, the property has become strategic. Sovereignty has crossed that line — and once a requirement is strategic, it stops being negotiable at renewal time and starts shaping architecture at design time.
Why both curves point the same way
It is tempting to frame boom and geopatriation as opposites. They are not. The same forces inflating the cloud bill — AI workloads, regulation, the sheer strategic weight of the software stack — are what make ownership of that stack matter more, not less. When cloud was a convenience, renting it was frictionless. Now that cloud is the business, “who can see, move, or switch off my workload” becomes a board-level question. The boom and the pullback are the same realisation arriving at two speeds.
This is where the architecture of what you run starts to matter as much as where you run it. A workload you can relocate is one you actually own — source-available, self-hostable, and free of a rented black box you cannot inspect. That is the geopatriation play expressed in software terms: not “leave the cloud” but “own the stack so you can put it wherever sovereignty, cost, or latency demands.”
The regional split: hyperscaler-led vs. sovereignty-first
The map divides cleanly. North America is riding the hyperscaler boom with the least sovereignty friction; Europe, the UK and the Gulf are leading the pullback; Asia’s fast-growing markets are increasingly building locally rather than importing capacity.
| Region | Cloud / sovereignty posture (2026–2027) |
|---|---|
| United States | Largest cloud/SaaS market; hyperscaler-led; least sovereignty friction — riding the $850B boom. |
| Canada | Mature North-American market; aligns with US cloud/SaaS trends; growing data-residency interest. |
| EU | Sovereignty epicentre; NIS2 and France’s “Cloud de Confiance” driving geopatriation; OVHcloud, Scaleway, Hetzner, Exoscale as alternatives. |
| UK | Mature market under EU-style sovereignty and data-residency pressure; strong fintech and retail-media demand. |
| Middle East / Gulf | Heavy sovereign-cloud demand; part of the European+Middle-Eastern geopatriation cohort (5%→75% by 2030). |
| ASEAN / Southeast Asia | Rising sovereign-AI and local cloud build-outs alongside fast consumer-internet growth. |
| South Asia / India | Local build-outs on a vast, under-penetrated base; sovereignty and residency interest rising. |
| China | State-directed, domestically controlled cloud and AI infrastructure by default. |
| Latin America | Fastest-growing regional market at 12.2% (2025); cloud adoption climbing off a lower base. |
Sovereign cloud at ~$80B in 2026 is still small against the $850B whole — but at a 5%-to-75% adoption slope, it is the fastest-moving posture on the board. The operators who win 2027 will run on the boom while keeping the option to step off it.
Own the stack, not just rent the cloud
If geopatriation is the strategy, self-hosted and source-available is the tactic — and this is where a proportionate, honest recommendation belongs. VBWD is built for exactly this posture: a self-hosted, source-available full-stack SaaS SDK with an agnostic core and toggleable plugins, invoice-centric commerce, a provider-agnostic payment core (including non-custodial crypto), MCP-native and GDPR-first, multi-tenant by design. Because plugins toggle without a restart, you reshape what the platform does at runtime instead of re-provisioning it. And because it is source-available and self-hostable, “relocate the workload for sovereignty” is a deployment decision, not a vendor negotiation — the same move a geopatriating enterprise makes, available to a startup.
The point is not that everyone should leave the hyperscalers; the $850B says most spending will not. The point is optionality. A stack you own can ride the boom in a public region today and satisfy NIS2 in a sovereign one tomorrow — no black box to rent, no rewrite to escape. The design is documented at vbwd.cc/docs, with the project at vbwd.cc and the source at github.com/VBWD-platform/vbwd-sdk-public.
Cloud in 2027 is a $1T market pulling in two directions at once. Spend follows the hyperscalers; control follows the sovereignty curve. The firms that thrive will refuse to choose — running on the boom while owning the stack that lets them leave.
Written for Red Robot with AI assistance and human editing. Figures from the firms cited; forecasts are estimates, not guarantees.


